
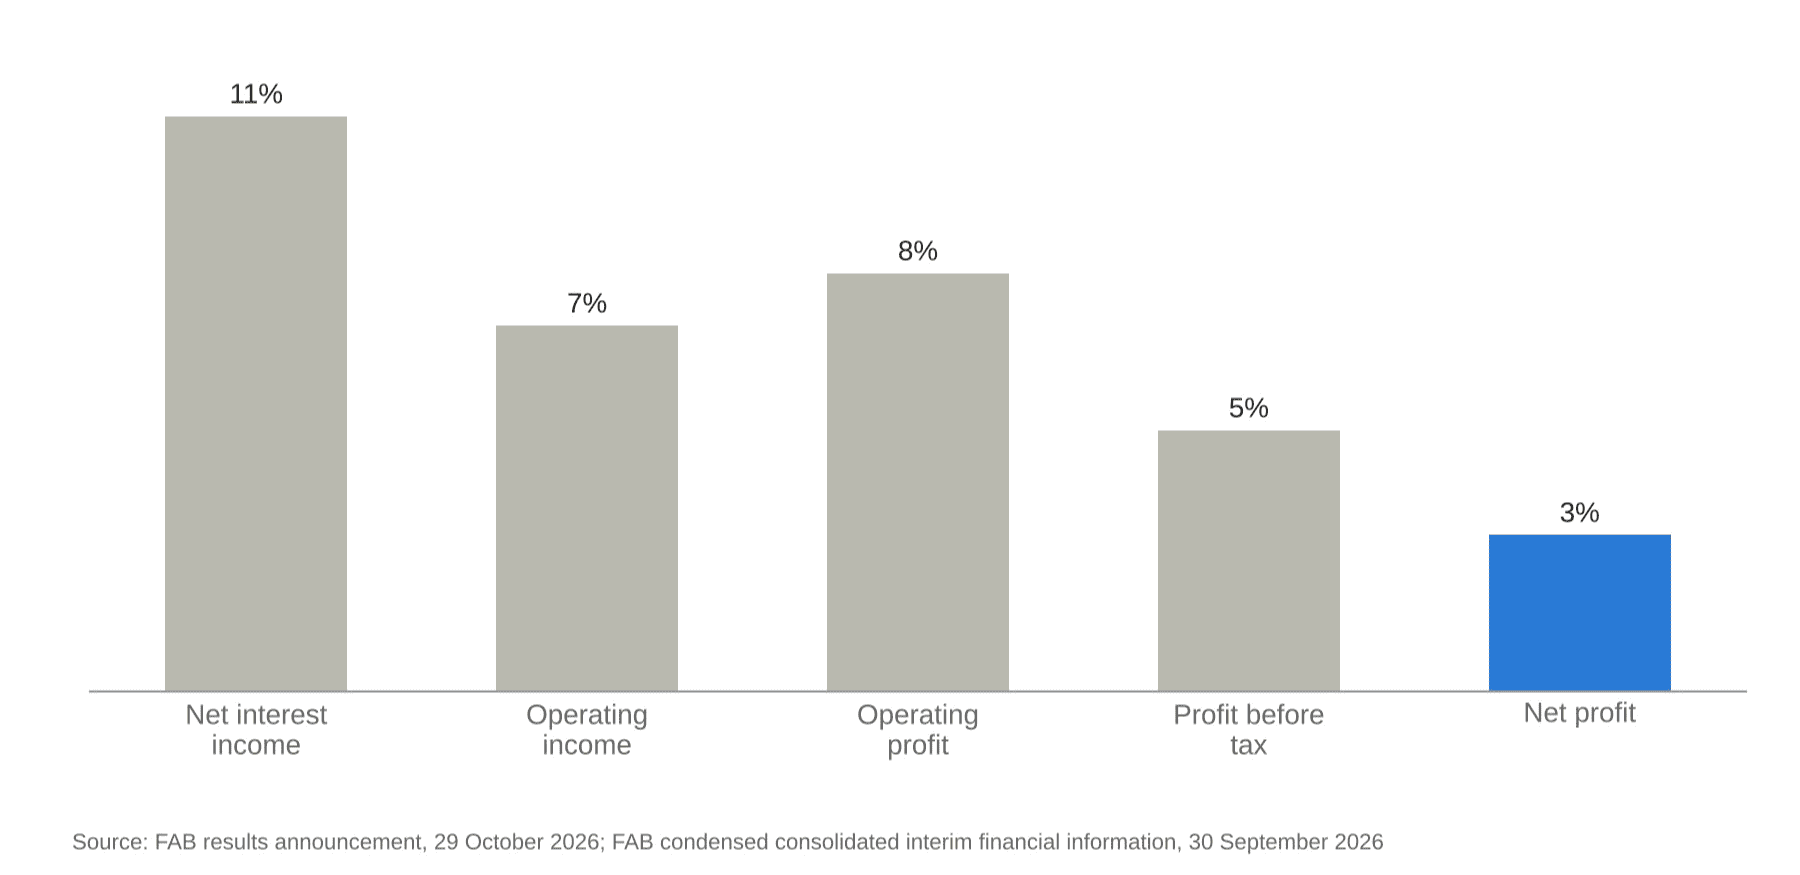
First Abu Dhabi Bank's (FAB) earnings tell two different growth stories. Net interest income, including Islamic financing income, rises 11% year on year to AED 16.98 billion for the nine months to 30 September 2026, but profit attributable to shareholders increases by just 3% to AED 16.46 billion. Operating income grows 7% to AED 29.71 billion, while return on tangible equity stands at 18.6%. The difference between revenue growth and bottom-line performance makes the results worth examining, particularly for UAE ETF investors. FAB represents 16.09% of the Lunate FTSE ADX 15 ETF (CHADX15), making it the fund's second-largest holding, and 12.88% of the Lunate S&P UAE UCITS ETF - Income (UAED), where it ranks first. On 9 November 2026, FAB also announced its acquisition of 100% of Bahrain-based Yasira Financial Services, expanding its securities services business.
FAB's 9M 2026 financial performance
FAB's year-on-year growth slows from 11% in net interest income to 3% in shareholder profit
The third quarter is stronger than the nine-month trend. Profit before tax rises 9% to AED 7.01 billion, while profit attributable to shareholders increases 6% to AED 5.74 billion, marking a quarterly record.
Why did FAB's net profit grow just 3% in 9M 2026?
Operating profit grows 8%, but profit attributable to shareholders increases by just 3%. Higher impairment charges and tax expenses account for much of the difference. The net impairment charge rises to AED 3.10 billion from AED 2.33 billion. This includes an AED 350 million expected credit loss (ECL) overlay reflecting uncertainty arising from the ongoing regional conflict. Income tax expense rises to AED 3.70 billion from AED 3.20 billion, which FAB's chief financial officer links to a higher contribution from the international business.
That international business is a growth driver in its own right. International revenue grows 31% and now makes up 22% of group revenue, while non-interest income makes up 43% of operating income. Operating expenses of AED 6.40 billion equal about 21.5% of operating income. Net interest margin is 1.93% for the nine months, up 5 basis points, although the third quarter margin of 1.85% is lower than the second quarter. A chart of growth rates down the income statement, from 11% at net interest income to 3% at net profit, shows the narrowing at a glance.
FAB's loan growth, deposits and capital adequacy in 2026
Gross loans stand at AED 697 billion before interest in suspense and provisions. FAB holds AA minus or equivalent ratings with stable outlooks from Moody's, Fitch and S&P. Shareholders approved an FY2025 cash dividend of AED 0.80 per share at the AGM on 11 March 2026, amounting to approximately AED 8.84 billion.
FAB expands its securities services business in Bahrain
FAB announced the acquisition of 100% of Yasira Financial Services B.S.C. (C), a Bahrain-based fund administration and trust services platform, according to WAM via The Gulf Times. Yasira supports public asset, private equity, venture capital and real estate funds. FAB plans to rebrand Yasira and integrate it into its broader Securities Services franchise, combining its fund administration capabilities with the bank's existing custody, cash management and foreign exchange services.
FAB has not disclosed the transaction value or identified the seller. The financial contribution of Yasira to FAB's earnings therefore cannot yet be assessed. Our earlier piece on FAB joining the ADX clearing ecosystem as a general clearing member covers the market infrastructure side of the same franchise.
How FAB's earnings affect UAED and CHADX15 ETF exposure
FAB ranks first in UAED and second in CHADX15 by portfolio weight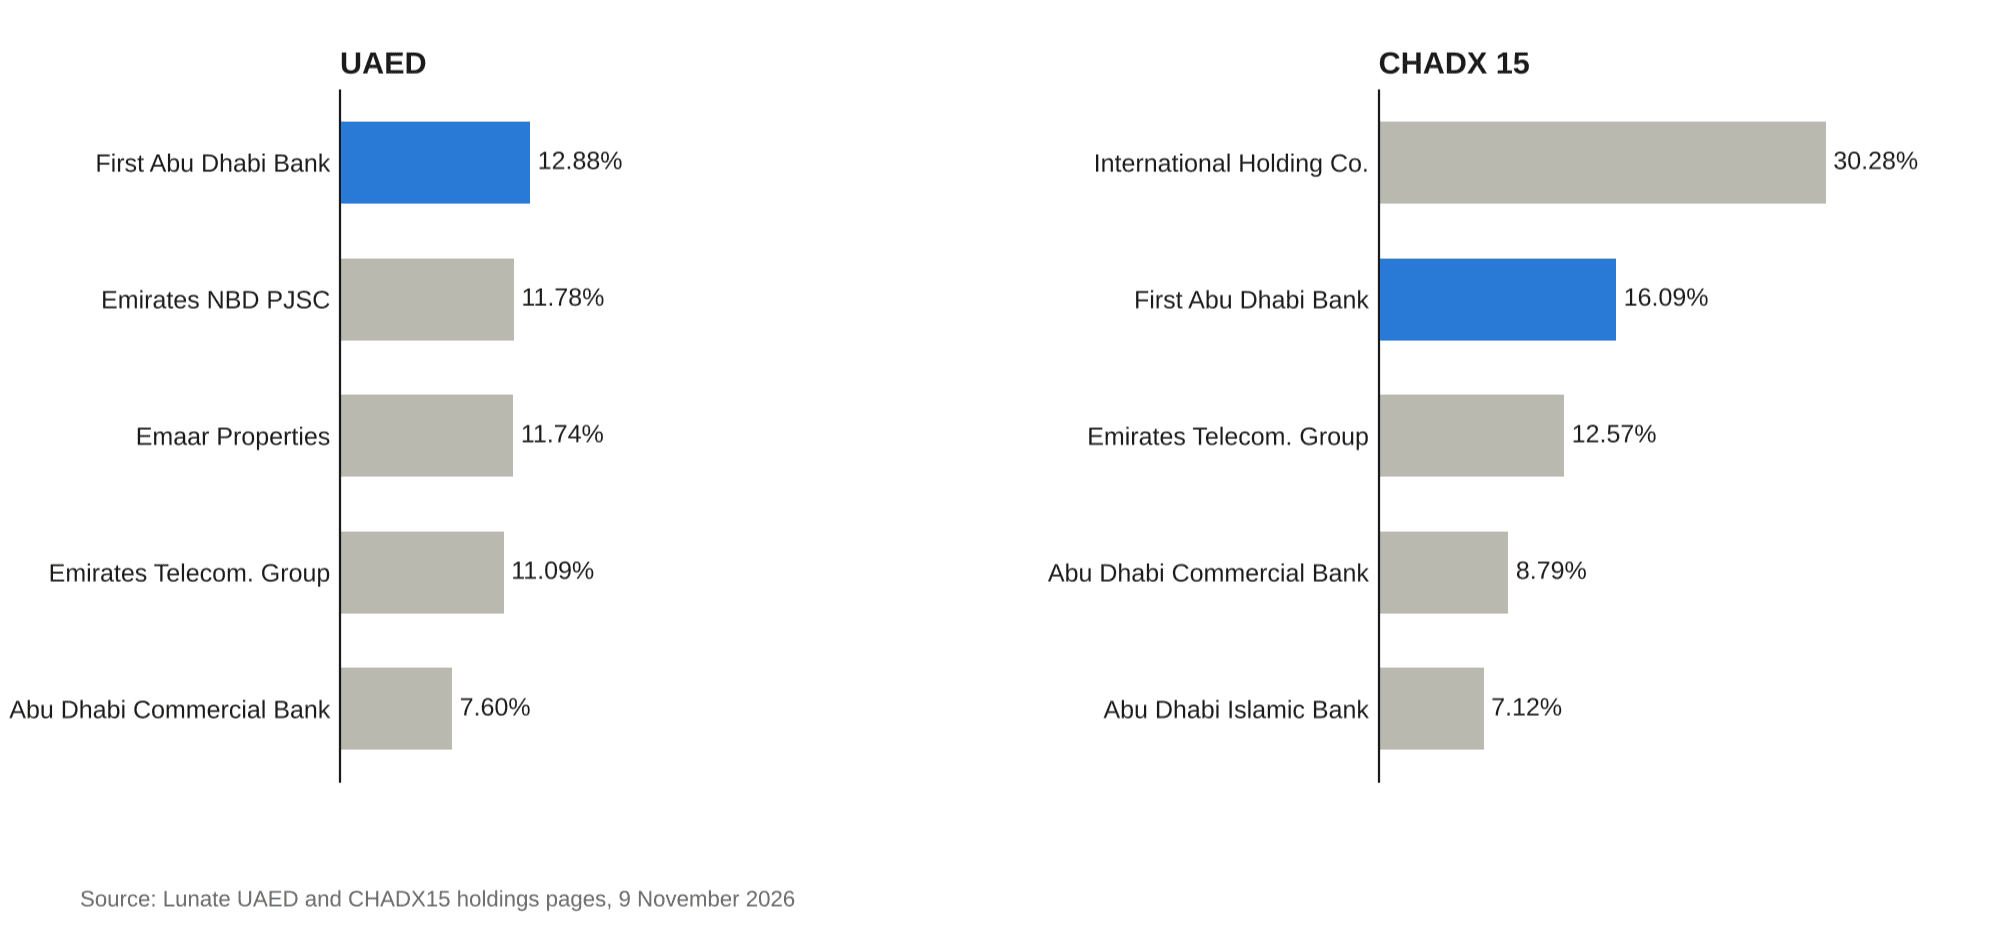
In CHADX15, FAB and IHC together account for 46.37% of the fund. In UAED, the top four holdings (FAB, Emirates NBD at 11.78%, Emaar Properties at 11.74% and e& at 11.09%) account for 47.49%. A chart of the top five holdings in each fund, with FAB highlighted, shows how differently the two funds are built around the same bank.
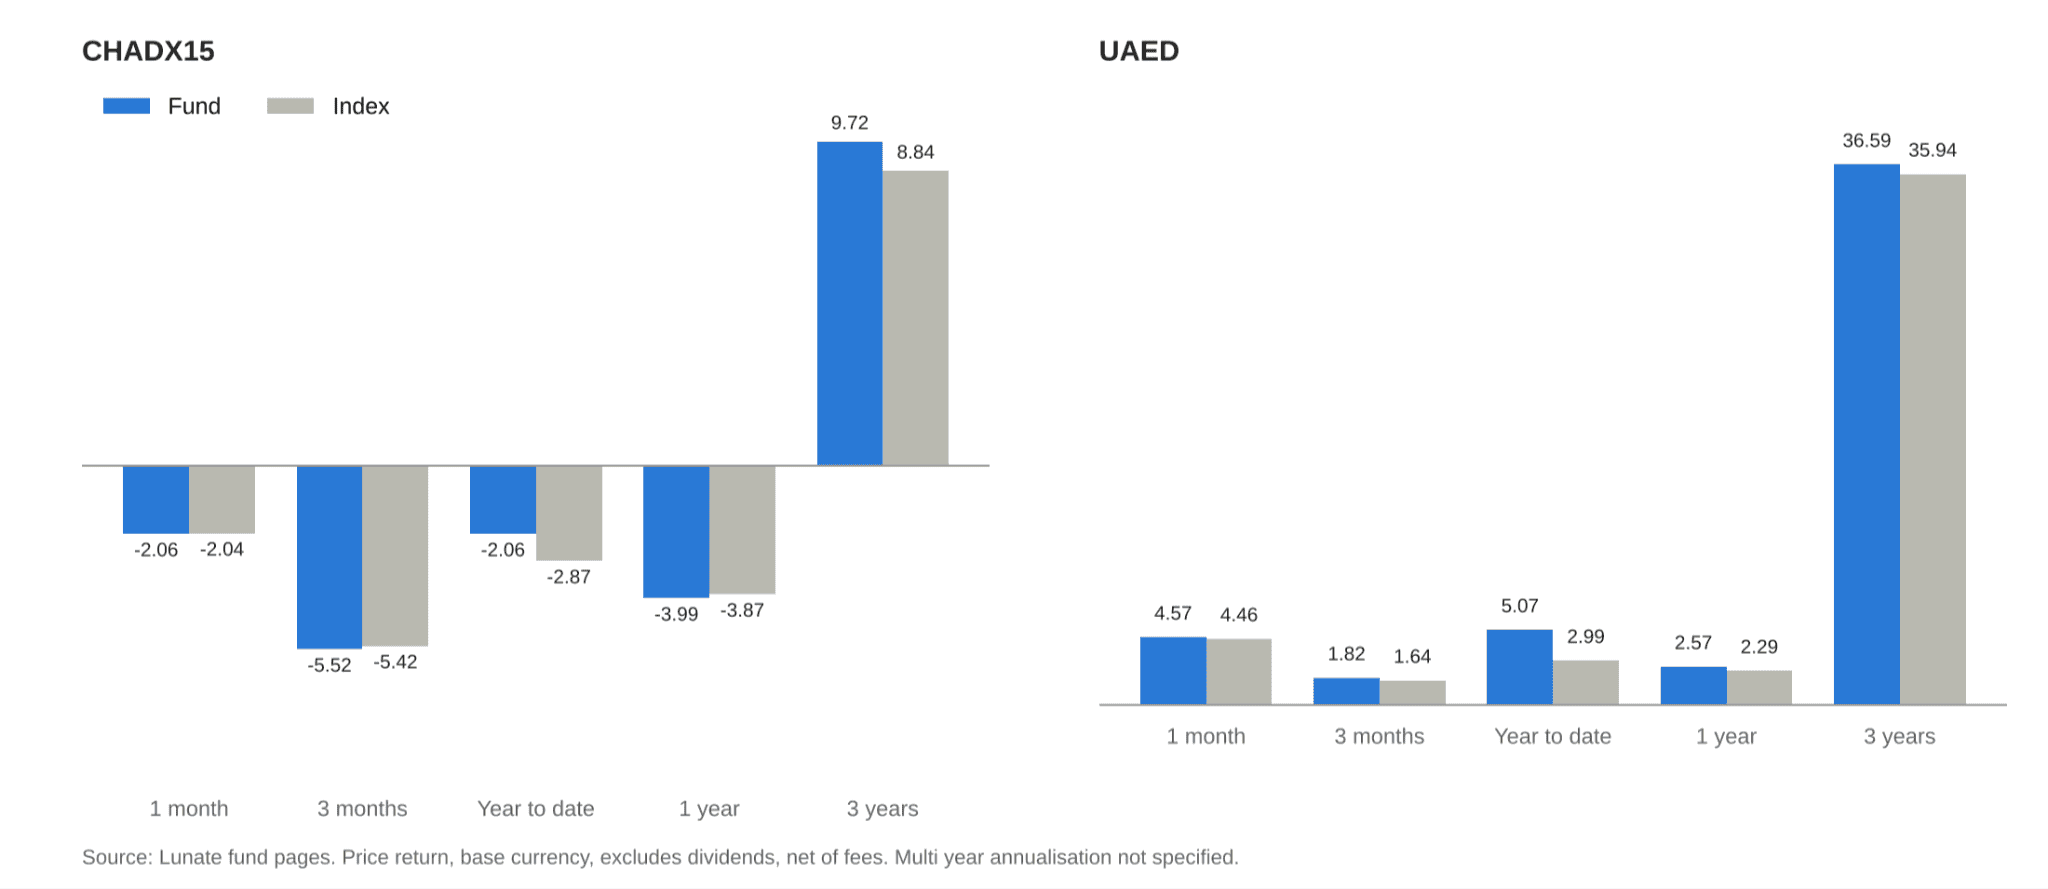
The figures below are price returns in each fund's base currency, exclude dividend distributions and are net of fees, as of 9 November 2026. FAB's AED 0.80 dividend is therefore not in them.
UAED leads its index over all four periods, while CHADX15 trails over one month and one year and leads over year-to-date and three years. The source does not specify whether the multi-year returns are annualised. The data available here does not include a reliable FAB share price move after the results, so this post draws no direct link between the earnings and the funds' recent returns.
FAB leads UAED holdings as its top four stocks account for 47.49%
What to watch
Management expects the fourth quarter net interest margin to stay resilient, with some potential for modest expansion. It estimates that a 25 basis point parallel move in rates changes net interest income by AED 200 million to AED 250 million before management actions. For UAED and CHADX15 holders, the key consideration is concentration. FAB's earnings, margins, and share price have a direct influence on both funds, and the influence is larger in CHADX15, where one bank is 16.09% of assets. This is not investment advice.